A cash flow forecast answers one question: on any given week in the next three months, will there be enough money in the account to cover what has to go out of it?
Your profit and loss statement cannot answer that. It records a sale in the month you invoiced, not the month you got paid, and it says nothing about the GST you are holding on behalf of the ATO or the loan principal that is not an expense at all. Profitable businesses run out of cash regularly, and almost always with some warning that nobody was looking for.
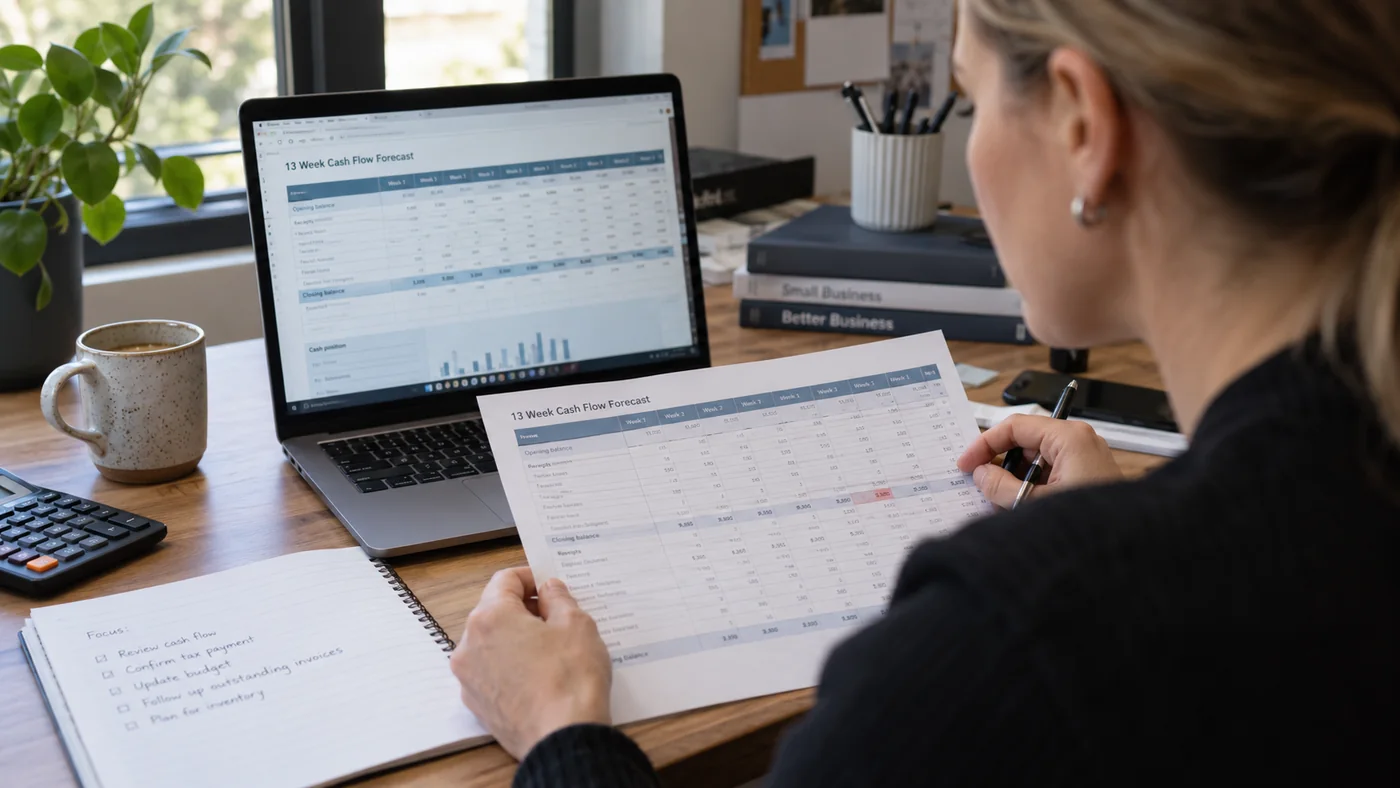
Download the Template
Download the 13 week cash flow forecast template (CSV)
It opens in Excel, Numbers or Google Sheets. The totals, net movement and closing balances are live formulas, so each week's closing balance carries into the next week's opening balance automatically. You fill in the blank cells and the rest calculates.
The rows are already set up for an Australian small business, which mostly means the payment lines that catch people out are already there: PAYG withholding, super at 12%, the BAS payment and PAYG income tax instalments. There is also a buffer row that flags any week where the closing balance drops below the minimum you want to hold, and a short summary underneath reporting the lowest balance in the quarter and how many weeks breach zero or the buffer.
Why Thirteen Weeks
Thirteen weeks is a quarter, and a quarter is the natural unit for an Australian business because it is how the BAS cycle works. A thirteen week view always contains exactly one BAS payment, which is usually the largest single outflow in the period and the one most often forgotten.
Weekly rows matter more than the horizon does. A monthly forecast can show a comfortable surplus for a month in which you were overdrawn for eleven days, because the big receipt landed on the 28th and the wages went out on the 5th. Averaging hides exactly the thing you are trying to see.
If you only take one thing from this: the resolution of the forecast has to be finer than the gap between your largest outflow and your largest inflow. For most businesses that means weekly.
Start With the Real Balance
The opening balance in week one is the actual cleared cash across all business accounts on the day the forecast starts. Not the balance in your accounting software, which may not have reconciled. Not the balance including a deposit that has not settled. The cleared figure.
Everything downstream inherits this number, so an opening balance that is $4,000 optimistic produces a forecast that is $4,000 optimistic in all thirteen weeks. It is worth two minutes in the banking app.
If you hold a separate account for GST and PAYG withholding, and you should, include it but be honest that it is not spendable. The buffer row at the bottom of the template is the right place to reflect that: set the minimum you want to hold at the level of the tax you are carrying, and the template will flag any week where you dip into it.
When the Money Actually Arrives
This is where most forecasts go wrong, because people forecast sales rather than receipts.
A café takes $8,000 in a week. The cash portion is in the till that day. The card portion settles one to three business days later depending on the processor, so a strong Saturday lands in the account on Tuesday. Across a week that difference rarely matters. Across the week you have to pay rent, it can.
A consultant invoices $22,000 on 1 June on 30 day terms. That is not June cash. It is early July cash, and only if the client pays on time. The template has separate rows for receipts within terms, 30 days overdue and 60 days overdue for exactly this reason: you are forced to make an explicit assumption about each bucket rather than one optimistic assumption about all of them.
Use your own debtor history rather than the stated terms. If a particular client has paid at day 45 for two years, forecast day 45. Building in the delay you already know about is not pessimism, it is accuracy, and it is the single highest-value thing you can do to a forecast.
Do not forget the receipts that are not sales: a GST refund, an equipment sale, a loan drawdown, money you put in yourself. They belong in the "other" row, in the week the funds actually land.
The Payments That Are Not Negotiable
Most of the outflows in a small business have some give in them. You can delay a supplier order, defer a piece of equipment, push a subscription. The ones that have no give are the ones the template lists separately.
- Net wages. Whatever else happens, this goes out on the day it goes out.
- PAYG withholding. You withheld it from employees. It belongs to the ATO and is reported on your BAS.
- Super guarantee. 12% of qualifying earnings, and since 1 July 2026 it moves with each pay run rather than each quarter. More on this below.
- BAS. The net GST position plus PAYG withholding for the quarter. Quarterly lodgers are generally due 28 October, 28 February, 28 April and 28 July, with later dates where a registered tax agent lodges for you.
- PAYG income tax instalments. If you are in the instalment system these sit on the same BAS and are easy to overlook when you budget for "the GST bill".
The GST point is worth stating plainly because it causes more damage than any other single item. The GST you collect on sales is not revenue. It arrives in your account, sits there for up to three months looking like money, and then leaves. A business that spends it is borrowing from the ATO at an interest rate it has not agreed to.
What Payday Super Changed
If your forecast template predates July 2026, its super row is wrong.
Under the old rules super was paid quarterly, which meant four large outflows a year and, in between, a growing liability that sat in the bank account looking like working capital. From 1 July 2026 super must be paid at the same time as wages, and the contribution has to be received by the fund within seven business days of the qualifying earnings day. New employees and first contributions to a fund get 20 business days.
The total amount you pay across a year has not changed. What changed is that it now leaves in twelve or twenty-six small pieces instead of four large ones, and the money is no longer sitting in your account between quarters.
For a business that was, knowingly or not, using accrued super as short-term working capital, that is a genuine reduction in available cash. The forecast is where you find out whether that applies to you. The super row should now appear in every week you run payroll, not four times a year.
Note the seven business days runs to receipt by the fund, not to the day you press pay. Clearing house timing sits inside that window, so the payment has to leave earlier than the deadline suggests. For the detail, see our guide to payday super.
Reading the Forecast
Once it is filled in, the forecast is answering three questions.
- Does the closing balance go negative? The bottom of the template reports the lowest closing balance across the thirteen weeks and counts how many weeks fall below zero, and the weekly row shows you which ones. A forecast that dips in week nine gives you nine weeks to act, which is usually enough to fix it with a conversation rather than a loan.
- Does it drop below your buffer? Going to zero is not the threshold that matters. Going below the amount of GST and PAYG withholding you are holding is, because at that point you are spending money that is not yours.
- Is the low point structural or timing? A single bad week caused by BAS landing the same week as a quarterly insurance premium is a timing problem, and moving one of them fixes it. A balance that declines steadily across all thirteen weeks is not a timing problem and no amount of rescheduling will fix it.
That last distinction is the one worth being honest about. A forecast that trends down week after week is telling you the business is not covering its costs, and the useful response is to change the pricing, the cost base or the collection process, not to arrange finance to cover the gap.
Keeping It Honest
A forecast built once and never revisited is worse than no forecast, because it creates confidence without accuracy.
Update it weekly. It takes about fifteen minutes once it is set up: replace the estimates for the week just finished with what actually happened, roll a new week onto the end, and adjust anything you now know about. The point of the weekly comparison is not the forecast, it is learning where your own estimates are biased. Most people discover they are consistently optimistic about receipts and consistently forget one recurring payment.
Two habits make it considerably more useful:
- Forecast receipts conservatively and payments generously. If you are going to be wrong, be wrong in the direction that does not bounce a payment.
- Keep a separate line for anything genuinely uncertain rather than blending it into a larger row. A $30,000 contract that may or may not be signed should be visible as a single assumption you can switch off, not buried inside a sales figure.
Frequently Asked Questions
Is the template actually free?
Yes. It is a CSV file, there is no sign-up, and nothing is collected when you download it.
Will it work in Google Sheets?
Yes. Upload it to Drive and open it with Sheets, or use File then Import. The formulas carry across. The same file opens in Excel and Numbers.
Should I forecast weekly or monthly?
Weekly, for almost every small business. Monthly forecasts hide within-month shortfalls, and the within-month shortfall is the one that causes a dishonoured payment. Monthly is reasonable only if your inflows and outflows are both genuinely smooth, which is rare.
How is this different from a budget?
A budget is about profit over a year and uses accrual figures. A cash flow forecast is about the bank balance over the next quarter and uses only money moving in and out. A business can be on budget and still unable to pay wages on Thursday.
Do I include GST in the figures?
Yes. A cash flow forecast tracks actual bank movements, so receipts and payments go in GST inclusive, and the net GST you remit appears as its own payment on the BAS row. This is the opposite of how you would treat GST in a profit and loss statement, and mixing the two conventions is a common source of error.
What if my accounting software already does forecasting?
Use it, if you trust the underlying data. Software forecasts are driven by what is in your ledger, so they are only as good as your reconciliation and your debtor assumptions. Many produce a projection based on invoice due dates rather than actual payment behaviour, which is exactly the optimism this template is designed to strip out. A spreadsheet you understand beats a projection you do not.
My forecast shows a shortfall in six weeks. What now?
Six weeks is a good position to be in, because most of the levers still work. In rough order: chase overdue debtors, talk to suppliers about terms, move discretionary spending out of the affected week, and only then consider finance. If the shortfall is driven by a BAS payment you cannot meet, contact the ATO before the due date rather than after. Payment arrangements are routinely available and far easier to obtain before a debt is overdue.
Most cash flow problems are visible weeks before they bite. A forecast is simply the discipline of looking, and thirteen weeks at weekly resolution is enough to turn a crisis into a scheduling decision.
Trew North Accounting builds and reviews cash flow forecasts for businesses across bayside Melbourne, and sets up the reporting that keeps them accurate. See our guide to fixing cash flow problems, our bookkeeping and small business planning services, or get in touch.
This article is general information, not advice for your circumstances. Rates, thresholds and due dates change. Check current requirements with the ATO or with us before you rely on them.